Credirecto
CREDIRECTO Specialized pitch · 04
Credirecto · P2P Credit

Credit that levels up with you.

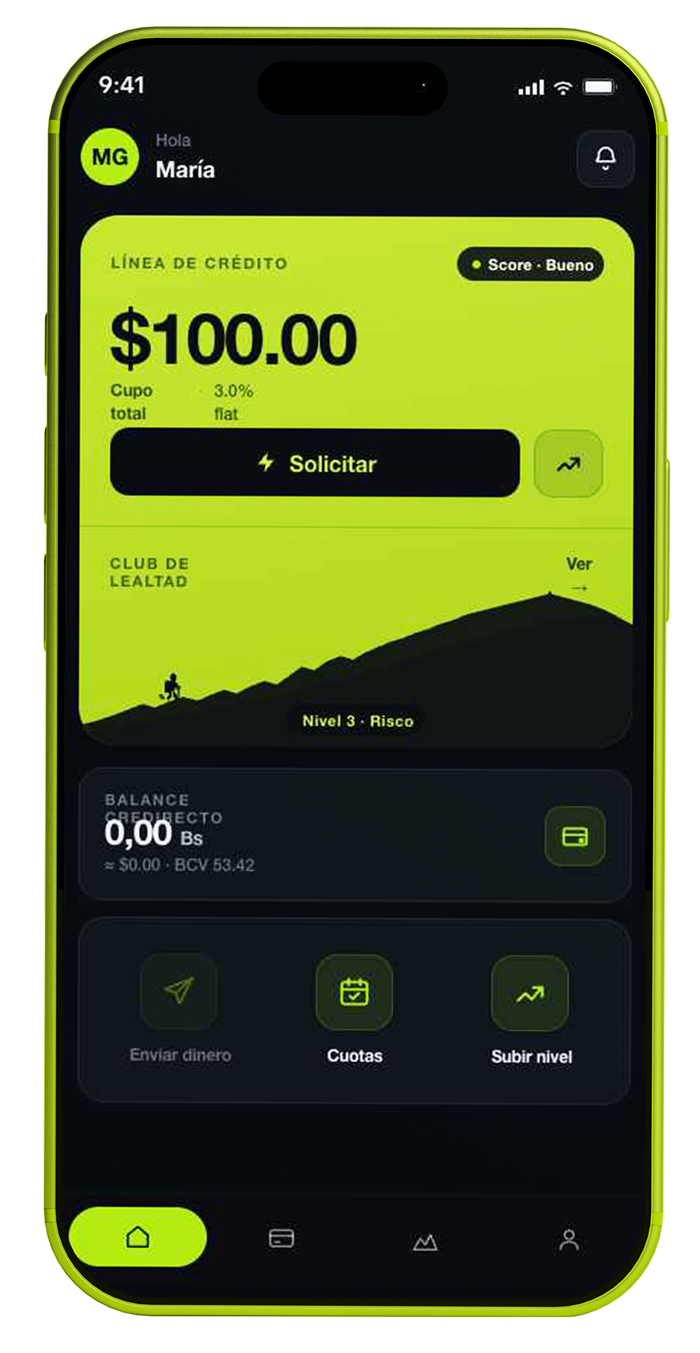
Credirecto is the peer-to-peer lending platform of the ecosystem. Flat 6.99% commission, transparent scoring, and a gamified tier mechanic with a mountain-climbing metaphor: each on-time repayment raises your limit and lowers your cost. Micro credits $50 - $5,000. Revolving micro-loans on 45-day cycles with a flat rate fee.
3%
Credit/GDP in VE (vs 40-50% LatAm)
6.99%
Flat, transparent commission
22d
Average loan cycle
$5–$5K
Limit range per tier
The problem

The credit gap largest in LatAm.

Venezuela has the most underdeveloped consumer credit system on the continent. Banks operate with a 73% legal reserve requirement — a structural restriction to place credit. People who need $50 to fill the tank have nowhere to turn.

Today in Venezuela

No formal credit. No alternatives.

  • Banks cover just 3% of GDP in credit (vs 40-50% LatAm)
  • 73% legal reserve prevents banks from placing capital
  • Credit cards virtually non-existent for new issuances
  • Informal loans with usury rates and zero protection
  • 30M people with zero useful recent credit history
With Credirecto

Fair, gamified, in-house credit.

  • Flat 6.99% commission — no fine print, no surprises
  • Own scoring based on PagoDirecto data (8 years, 500K users)
  • Gamified tiers: each repayment raises your limit and lowers your cost
  • Limits from $5 — accessible to anyone, especially those who never had credit
  • Roadmap to pure P2P: marketplace of lenders and borrowers
How it scales

Two phases, one mountain.

We start with small tickets and own capital to validate scoring. We grow to larger tickets and pure P2P as behavioral data feeds the model.

Phase 1 · MVP

$5 – $50

Revolving micro-loans operating on 45-day cycles with a flat rate fee. Own capital. We validate scoring and behavior.
Phase 2 · Scale

$50 – $5.000

Negotiated commission · Extended terms · Own capital + external balance sheet. Large tickets with mature scoring.

Phase 3 · Pure P2P

Marketplace

Individual lenders contribute capital. Credirecto operates as rail, scoring and collection. Flat fee on the match.

The mechanic

Each tier, one step up.

The Ávila metaphor: you start in the valley, climb with each repayment. Higher limit, better rate, more trust. Credit as reward, not trap.

Tier 1
Valley

$5 – $20

Tier 2
Trail

$20 – $100

Tier 3
Summit

$100 – $500

Tier 4
Peak

$500 – $2.000

Tier 5
Top

$2.000 – $5.000

The moat

Why Credirecto can do it and a new fintech can't.

Credit in emerging markets is 80% scoring, 15% collection and 5% capital. We have all three already built.

  • Unique own data: 8 years of real transactional patterns from PagoDirecto. Frequency, ticket, vertical, recurrence. The input no competitor has from zero.
  • Transparent scoring: the user sees why they went up or down. Builds trust, cuts default, drives loyalty. Different from opaque bank scoring.
  • Built-in distribution: Credirecto is offered inside the PagoDirecto app. Effective CAC close to zero.
  • Collection integrated into the rail: repayment is deducted from the user's PagoDirecto payment flow. Near-zero friction. Expected default: low.
  • Ethical product, differentiated brand: "Believe to grow" is not just a slogan — it's the proposition. In a market plagued by predatory lenders, trust is the moat.
Why now

Consumer credit is reactivating.

2025-2026 mark the first expansive credit-book cycle in years in Venezuela. Banks can't absorb the demand. Fintechs can — and we take the trust brand now, or someone else does.

01 · Demand

Loan book +46% YoY

Credit grew +46% between March 2025 and March 2026. It's the first serious expansive cycle in years. Demand is there, supply is not.

02 · Structure

3% of GDP in credit

Credit/GDP ratio is ~10–15x lower than LatAm average. Multi-billion-dollar structural gap.

03 · BNPL

+250% YoY · $7.7B

BNPL grew +250% in 2025. Validation that Venezuelan consumers do take consumer credit when it's accessible and simple.

04 · Limited banking

73% legal reserve requirement

Banks can't place capital. The space for credit fintechs is structural, not cyclical.

05 · Ecosystem

Synergy with PagoDirecto

500K users, $1.7M monthly GMV are the natural origination base for credit and the natural collection rail.

06 · Stablecoins

Capital at stable rate

$44.6B in crypto/stablecoins in VE. Enables P2P capital in USDT with FX risk neutralized for both sides of the loan.

Venezuela's fair credit has a name. And it grows with whoever pays it.

Credirecto reactivates supervised consumer credit on top of the rail. Under the Embassy pilot, every credit flow is screened and reportable — closing the gap that Venezuelan banks left open.

NEXT STEP

Agenda 30 minutos con el equipo.

Reserva directo en el calendario. Confirmación inmediata.

Agendar 30 min
Calendly · Confirmación inmediata
Continue the tour

Meet the other brands in the ecosystem.

← Back to main pitch